FHA and VA Loans on New Construction: What Buyers in North Port and Port Charlotte Should Know
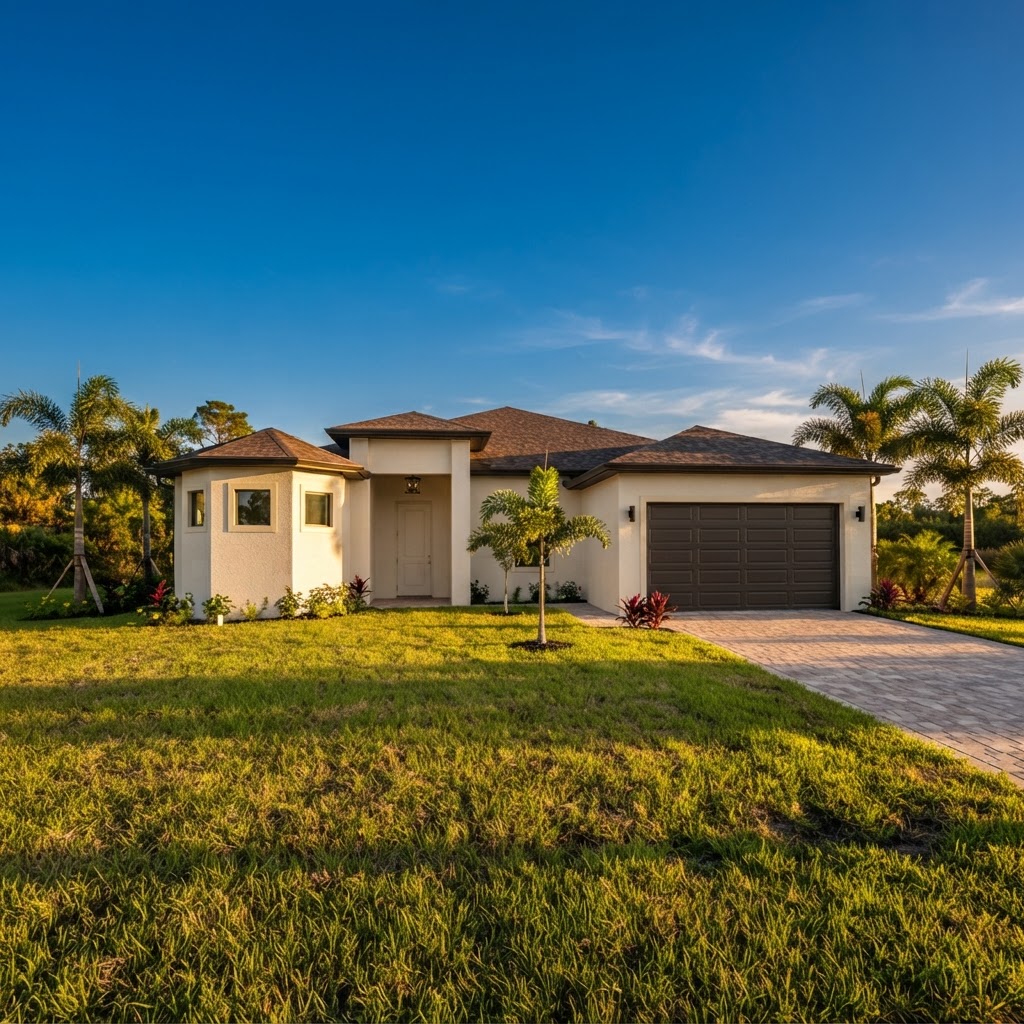
Many buyers assume government-backed loans are only for older, resale homes. In fact, FHA and VA financing can both be used to buy a brand-new home. The difference with a new build is mostly paperwork and timing: the lender needs to see that the home was built to standard and is fully complete before closing. This guide explains the basics in plain language. It is general information, not lending advice; your lender sets the final requirements for your loan.
FHA loans on a new home
FHA loans are insured by the Federal Housing Administration. The minimum down payment is 3.5% for borrowers with a credit score of 580 or higher, which is why FHA is popular with first-time buyers. FHA loans include mortgage insurance, and your lender will explain how it applies to your loan.
The builder paperwork
For a home that is under construction or was completed less than a year ago, HUD’s Single Family Housing Policy Handbook (4000.1) asks for extra documents, including a Builder’s Certification of Plans, Specifications and Site (form HUD-92541) and a Warranty of Completion of Construction (form HUD-92544), plus evidence the home was permitted and inspected, such as the building permit and certificate of occupancy, and a termite treatment report where required.
Why this matters for your down payment
Under the handbook, new homes that do not meet the required documentation can be limited to a 90% loan-to-value, meaning a larger down payment. Builders that permit and inspect every home through the local building department, and complete the paperwork, help buyers qualify for maximum financing. Ask your lender early which documents they need from the builder.
VA loans on a new home
VA home loans are guaranteed by the U.S. Department of Veterans Affairs for eligible veterans, active-duty service members and eligible surviving spouses. For eligible borrowers, a VA loan can mean no down payment and no private mortgage insurance. Some borrowers are exempt from the VA funding fee; that depends on the borrower, not the home.
What is different for new construction
Every VA purchase needs a VA appraisal, and the home must meet VA Minimum Property Requirements. For a home still being built, the loan cannot fund until the home is 100% complete and passes the final VA appraisal or inspection. Under VA Circular 26-25-1, builders no longer need a separate VA Builder ID to sell new or proposed construction to VA buyers, but they must still be properly licensed and meet state and local requirements.
Tips for using FHA or VA on a DCA home
- 1. Get pre-approved first, and tell your lender you are buying new construction so they can plan for the builder documents.
- 2. Ask about timing: if the home is still being built, your loan closes after completion and the final inspection.
- 3. Get a home inspection even on a new home; many buyers also schedule one before the 1-year workmanship warranty ends.
- 4. Ask about current incentives: DCA offers a $2,500 seller credit toward closing costs on select homes; contact us for current availability and terms.
Warranties that come with a DCA home
DCA homes include a 1-year workmanship and systems warranty and a 10-year structural warranty through a third-party warranty provider. If your lender asks about a ten-year protection plan for FHA, share the warranty details with them and ask whether it meets their requirements. See our Warranty page for coverage details.
Ready to see homes?
Browse homes for sale and coming soon, or review loan options on our Financing page.
Real estate agents with buyers using FHA or VA can bring them to any DCA home; see our For Agents page, and agents outside Florida can earn a referral at our agent referral program.
Frequently asked questions
Can I use an FHA loan to buy a brand-new home?
Yes. FHA loans can be used on new construction; the lender will need builder documents such as the HUD-92541 builder’s certification and proof of permits and inspections.
Can I use a VA loan on new construction?
Yes. The home needs a VA appraisal and must be 100% complete before the loan funds.
Does the builder need a VA Builder ID?
Not anymore for new or proposed construction under VA Circular 26-25-1, though builders must still meet state and local licensing rules.
Do I still need an inspection on a new home?
It is strongly recommended, both before closing and before your 1-year warranty ends.
Related links
Sources: HUD Single Family Housing Policy Handbook 4000.1, section II.A.8.i (New Construction); U.S. Department of Veterans Affairs Circular 26-25-1.